Project marketing specialists +64 9 802 7695 hello@kingdomrealty.co.nz
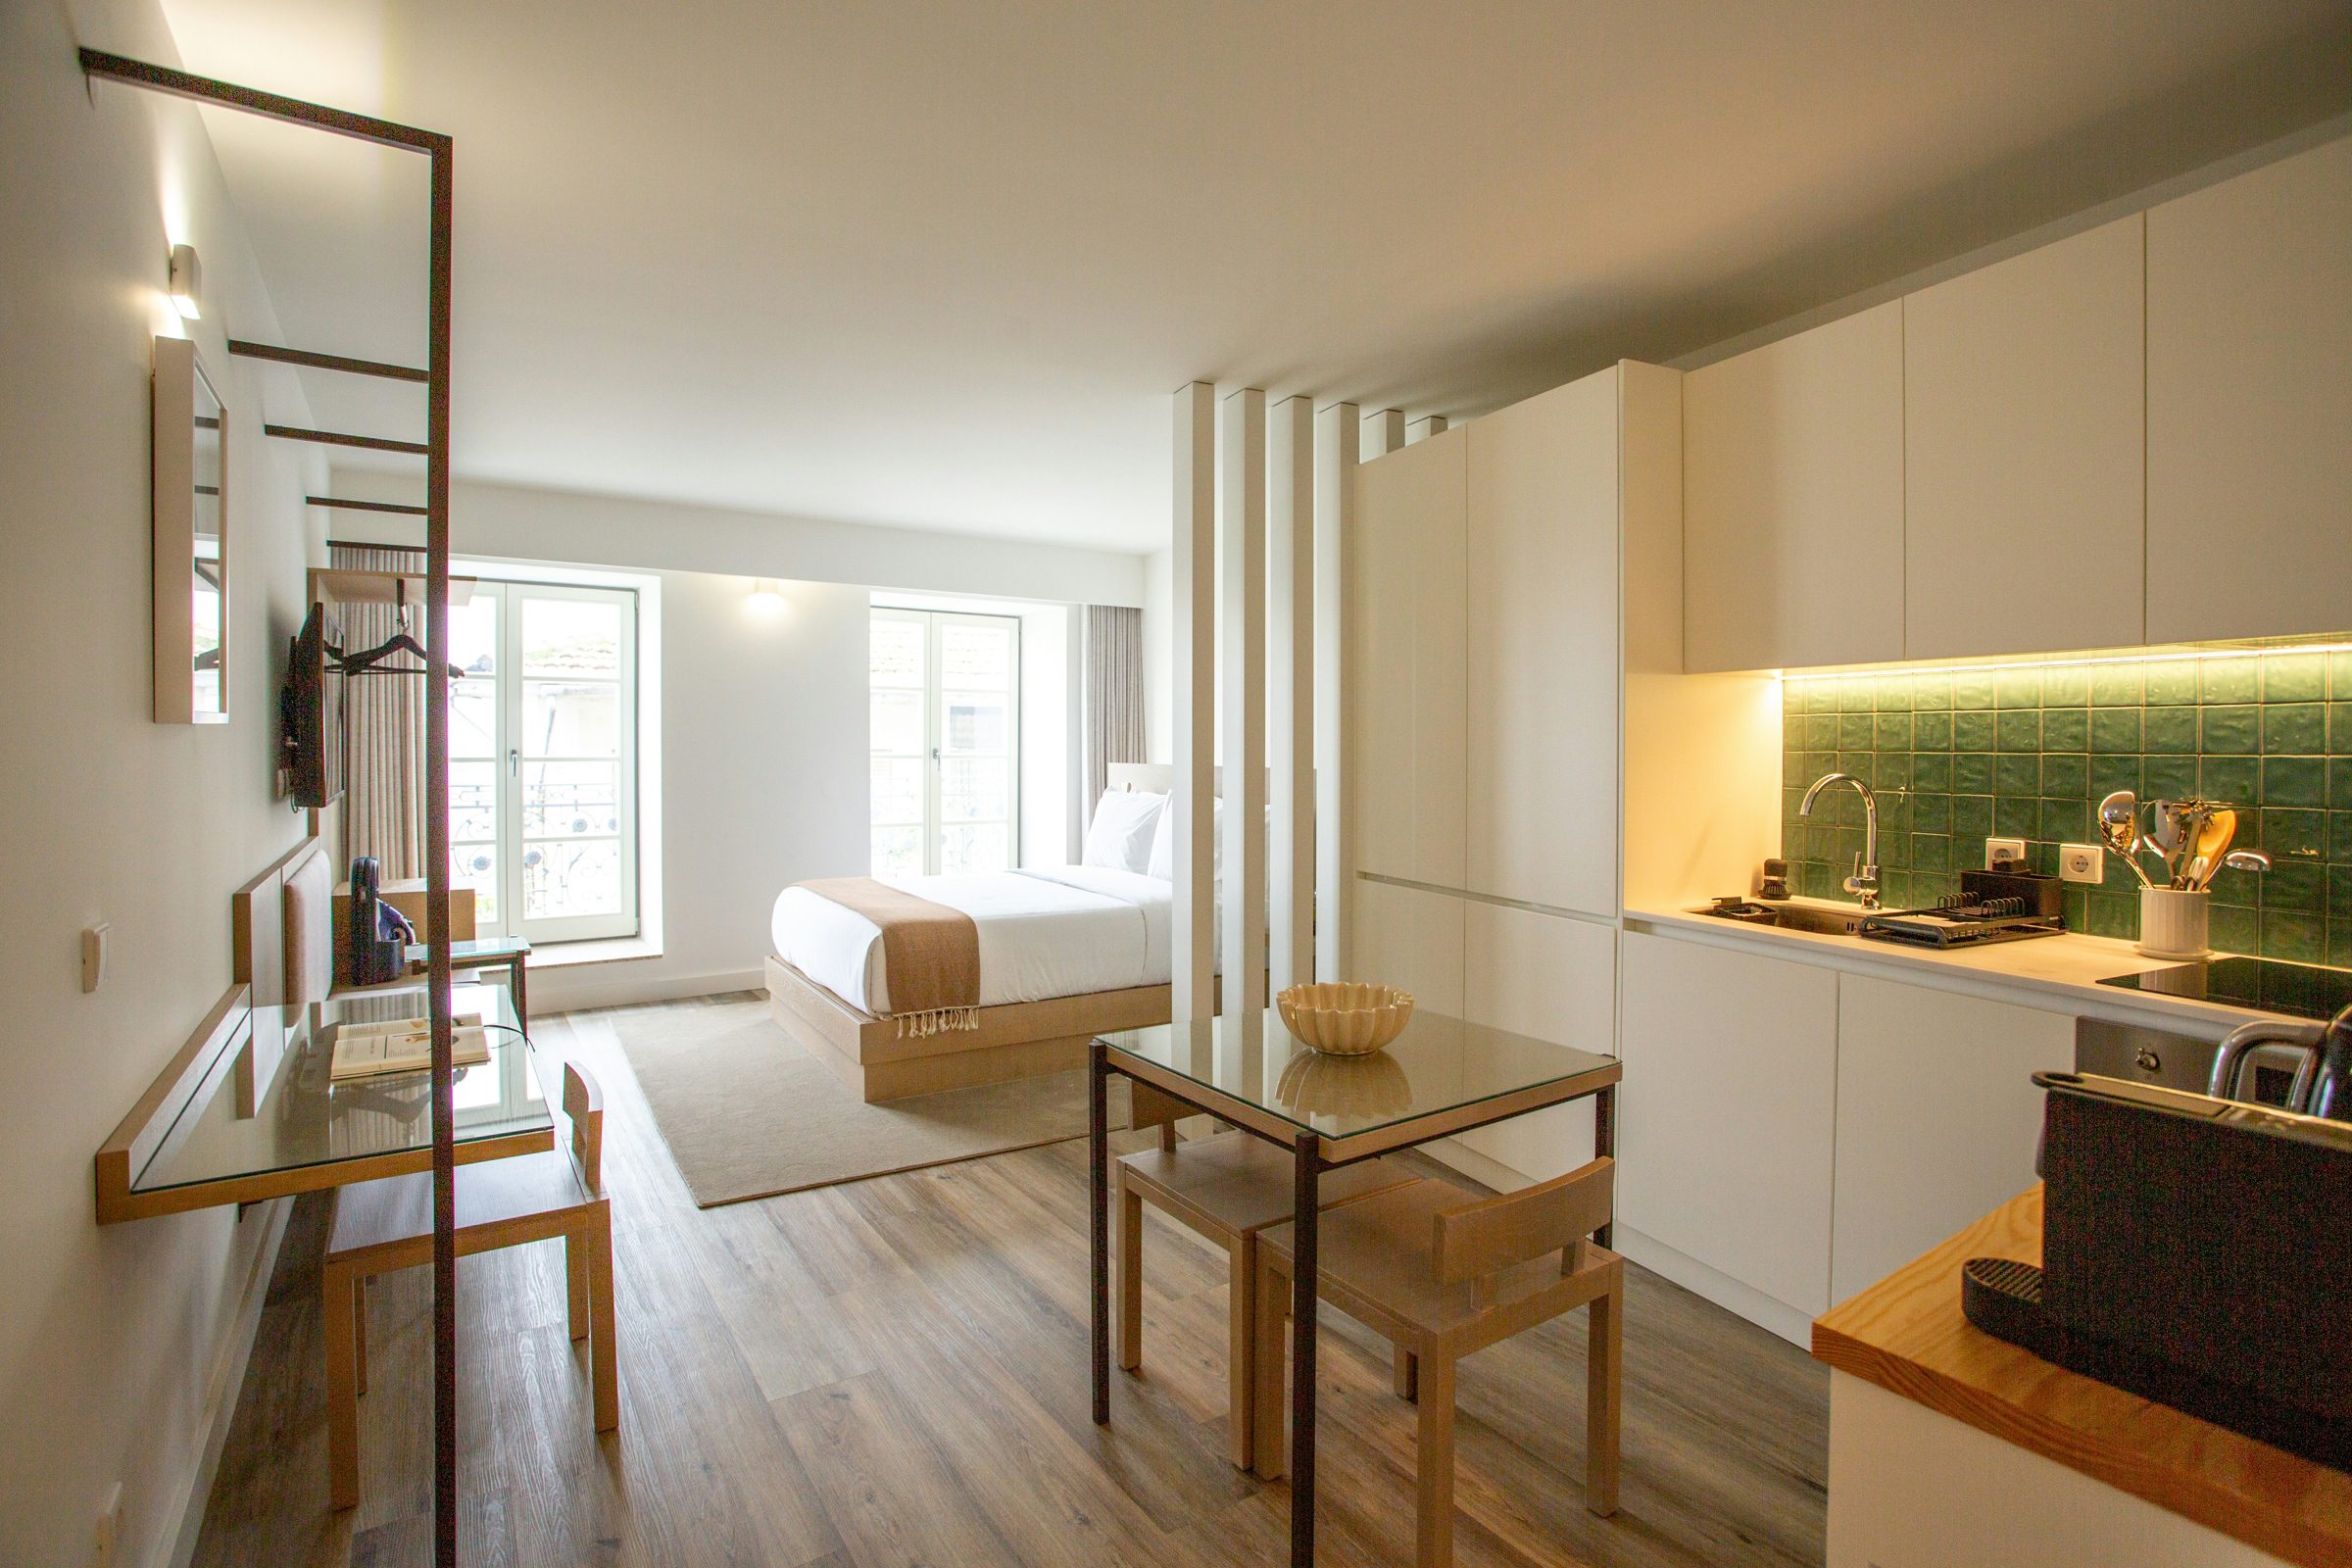
A new open plan apartment with the kitchen, dining table and living area in one room

Investors

New homes, with your eyes open.

A new build is simple to own: a price agreed in the contract, the cover the law gives a new home, and a 12-month defect repair period after completion. Here is how buying one as an investment works, and what twenty years of New Zealand homes looks like.

Powered by eXp New Zealand Licensed REAA 2008 From the first plans to the last key See what's selling now

$550m+

of property worked on over our careers, new homes and at auction

17+ years

in property between us, New Zealand and Australia

100%

focused on new builds, from the first plans to the last key

Investors buy new builds for the simplicity: a price fixed in the agreement, a known completion date and a home that needs nothing done to it. We cannot tell you what it will earn or what it will be worth. We can show you the homes, the plans and the dates, and walk you through the purchase.

01Why a new build

Four reasons investors choose new.

  • Value that can grow while it is built

    You agree today's price and settle on the finished home months later. When values rise in that time, the gain is yours before the first tenant moves in. Values can also fall, so it is a possibility, not a promise. The twenty years below show how New Zealand homes have moved over time.

  • A price agreed up front

    Some new homes are sold turnkey: one price for the finished home, agreed in the contract. Some are built on progressive payments, where you pay in stages as the build goes up. We tell you which is which before you sign, and your solicitor checks the agreement for any adjustment clause.

  • The cover the law gives

    Every new home comes with the warranties the Building Act 2004 implies into the building contract, and for 12 months after completion you can require the builder or the seller to fix a defect you tell them about in writing (Building Act section 362Q). Where a home also has a builder's guarantee, we tell you which one and show you where it is written.

  • A smaller deposit at the start

    A deposit on signing and the balance at settlement, with the build in between to line up your finance. Your adviser can tell you what the lending rules allow for a new build.

02Why property · New Zealand, 2006 to 2026

Up over twenty years. Not in a straight line.

That is the middle New Zealand sale, twenty years apart. $310,000 then, $750,000 now: 2.4 times, 4.5% a year, through a global financial crisis, a pandemic and the sharpest rate rises in a generation. Even the slowest ten-year stretch in the series, February 2007 to February 2017, still grew at 4.0% a year.

Property is one of the few things a bank will lend you most of the money for. Put $100,000 in a fund and your $100,000 does the work. Put it down as a deposit and it controls a home worth several times that, so the growth lands on the whole home, not just your slice. So does a fall. The catch is what it costs to hold: the interest, the rates, the insurance, minus the rent. That is the number that makes or breaks it, which is why your adviser should put the weekly cost in writing, line by line, before you buy anything.

The middle New Zealand home, August 2006

$310,000

The middle New Zealand home, August 2026

$750,000

What actually happened. REINZ median sale price, the middle of every sale in the country that month.
The twenty years, month by month

×2.4
$310,000 to $750,000, August 2006 to August 2026
4.5%
a year, compounding, before a dollar of rent
+$440,000
the August 2026 median less the August 2006 median: arithmetic on the REINZ record, price only

REINZ median sale price, all New Zealand, monthly, via interest.co.nz (chart 'Median price - REINZ'), August 2006 to August 2026, read 16 September 2026: $310,000 to $750,000, 2.4 times, 4.5% a year. Slowest and fastest are the lowest and highest rolling ten-year stretches on the same monthly REINZ series (February 2007 to February 2017, 4.0% a year; December 2011 to December 2021, 9.7% a year), each run for twenty years from $310,000 as arithmetic, not a prediction. The next-twenty view asks what would happen if the next twenty years matched the slowest decade or the last twenty years, which nobody can promise: the same arithmetic run forward from $750,000, an illustration of pace, not a forecast. Nobody knows what prices will do. Price only, no rent, no costs. The middle of the country, not any one house.

03The rules for new builds

Four rules that treat a new build differently.

  1. The bank can lend more of the price

    Lending on a new build is treated differently from lending on an existing home under the Reserve Bank's loan to value and debt to income rules. Every bank still runs its own test, so ask yours what applies to you.

  2. Interest is deductible again

    Interest on a loan for a rental property has been fully deductible against the rent since 1 April 2025, for new and existing homes alike. Your accountant can tell you what that means for your numbers.

  3. The bright-line test is two years

    Since 1 July 2024 the bright-line period is two years. Sell a rental inside it and any gain is taxed as income; hold it longer and the ordinary rules apply. Take advice before you buy.

  4. Healthy Homes, checked before you let it

    Every rental must meet the Healthy Homes standards: insulation, heating, ventilation, moisture and draughts. A new home is built to the current Building Code, which helps, but check each standard before the first tenant moves in. The Building Act's implied warranties can be enforced for up to ten years.

Rules as at October 2026. They change; your adviser and your accountant confirm what applies to you. We are a project marketing company and we do not give financial advice.

The catch is what it costs to hold.

Interest, rates, insurance, a body corporate levy where there is one, and a property manager if you use one, minus the rent. On a new build the maintenance line is usually lower in the early years, though it is never nothing. Put your own numbers on each line with your adviser before you sign.

04How it works

Buying off the plans, step by step.

The same five steps as any buyer, with your solicitor and your adviser alongside you.

  1. Pick the development, then the home: the plan, the floor, the aspect, the price. We'll show you what is still available.

  2. A sale and purchase agreement, checked by your solicitor, and a deposit held in trust until settlement.

  3. The home goes up. We send progress updates and tell you when the dates firm up, so your finance is ready when settlement is.

  4. Finance confirmed, a walk through the finished home, and any small fixes listed before you settle.

  5. Titles issue, the balance is paid, and the keys are yours.

Talk to us

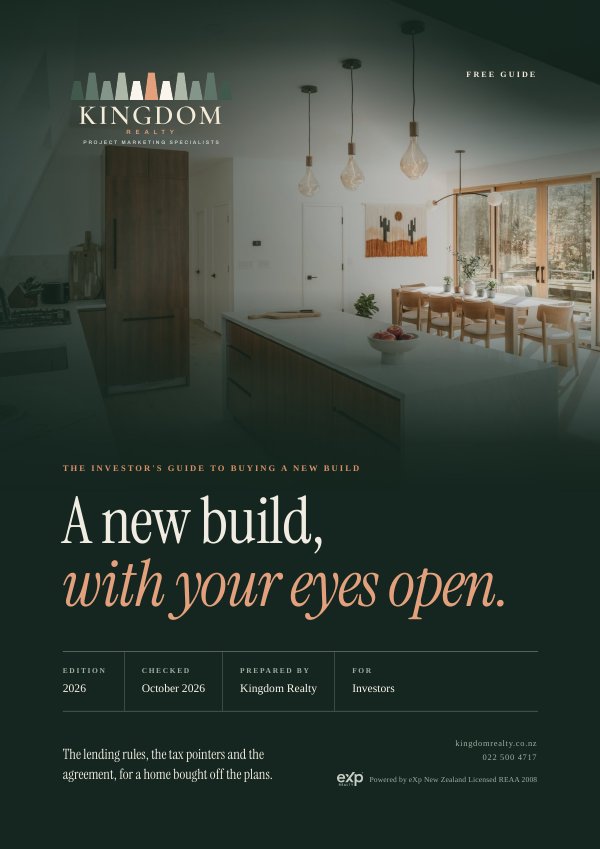
The cover of The Investor's Guide to Buying a New Build

Free guide for investors

The Investor's Guide to Buying a New Build

The lending rules and who may buy, the tenancy rules as they stand, the tax questions for your accountant, and what to read in the agreement.

  • What you know on day one, and what you do not
  • Checking the developer and the builder
  • The Reserve Bank's lending rules, and who may buy
  • The agreement, and what it costs to hold

Everything inside the guide

What to expect from us

Everything a buyer gets, and two things more.

  • A rent guide before completion

    We send a rent guide 60 days before settlement, for that suburb and home type, using Tenancy Services' market rent figures. A guide, not a promise.

  • A property manager, if you want one

    With your yes, we introduce you to a property manager, a separate business from Kingdom. Healthy Homes questions go to them, and tax to your accountant.

  • A call, fast

    We usually call within five minutes in calling hours (Monday to Friday, 8am to 6pm), and never later than one working day.

  • Your offer, answered

    Every written offer goes to the developer the same working day. If it is declined, you hear within one working day.

  • Through the build

    An update every month, a call every quarter, a finance check-in 90 days before completion, and any delay passed on the day we hear of it.

  • After the keys

    A call in the first week, and a reminder before the 12-month defect repair period ends.

  • The New Build Report

    Once a month: what is launching in Auckland, what building costs are doing and which rules have changed. Sign up.

05Developments that suit

Where investors are looking now.

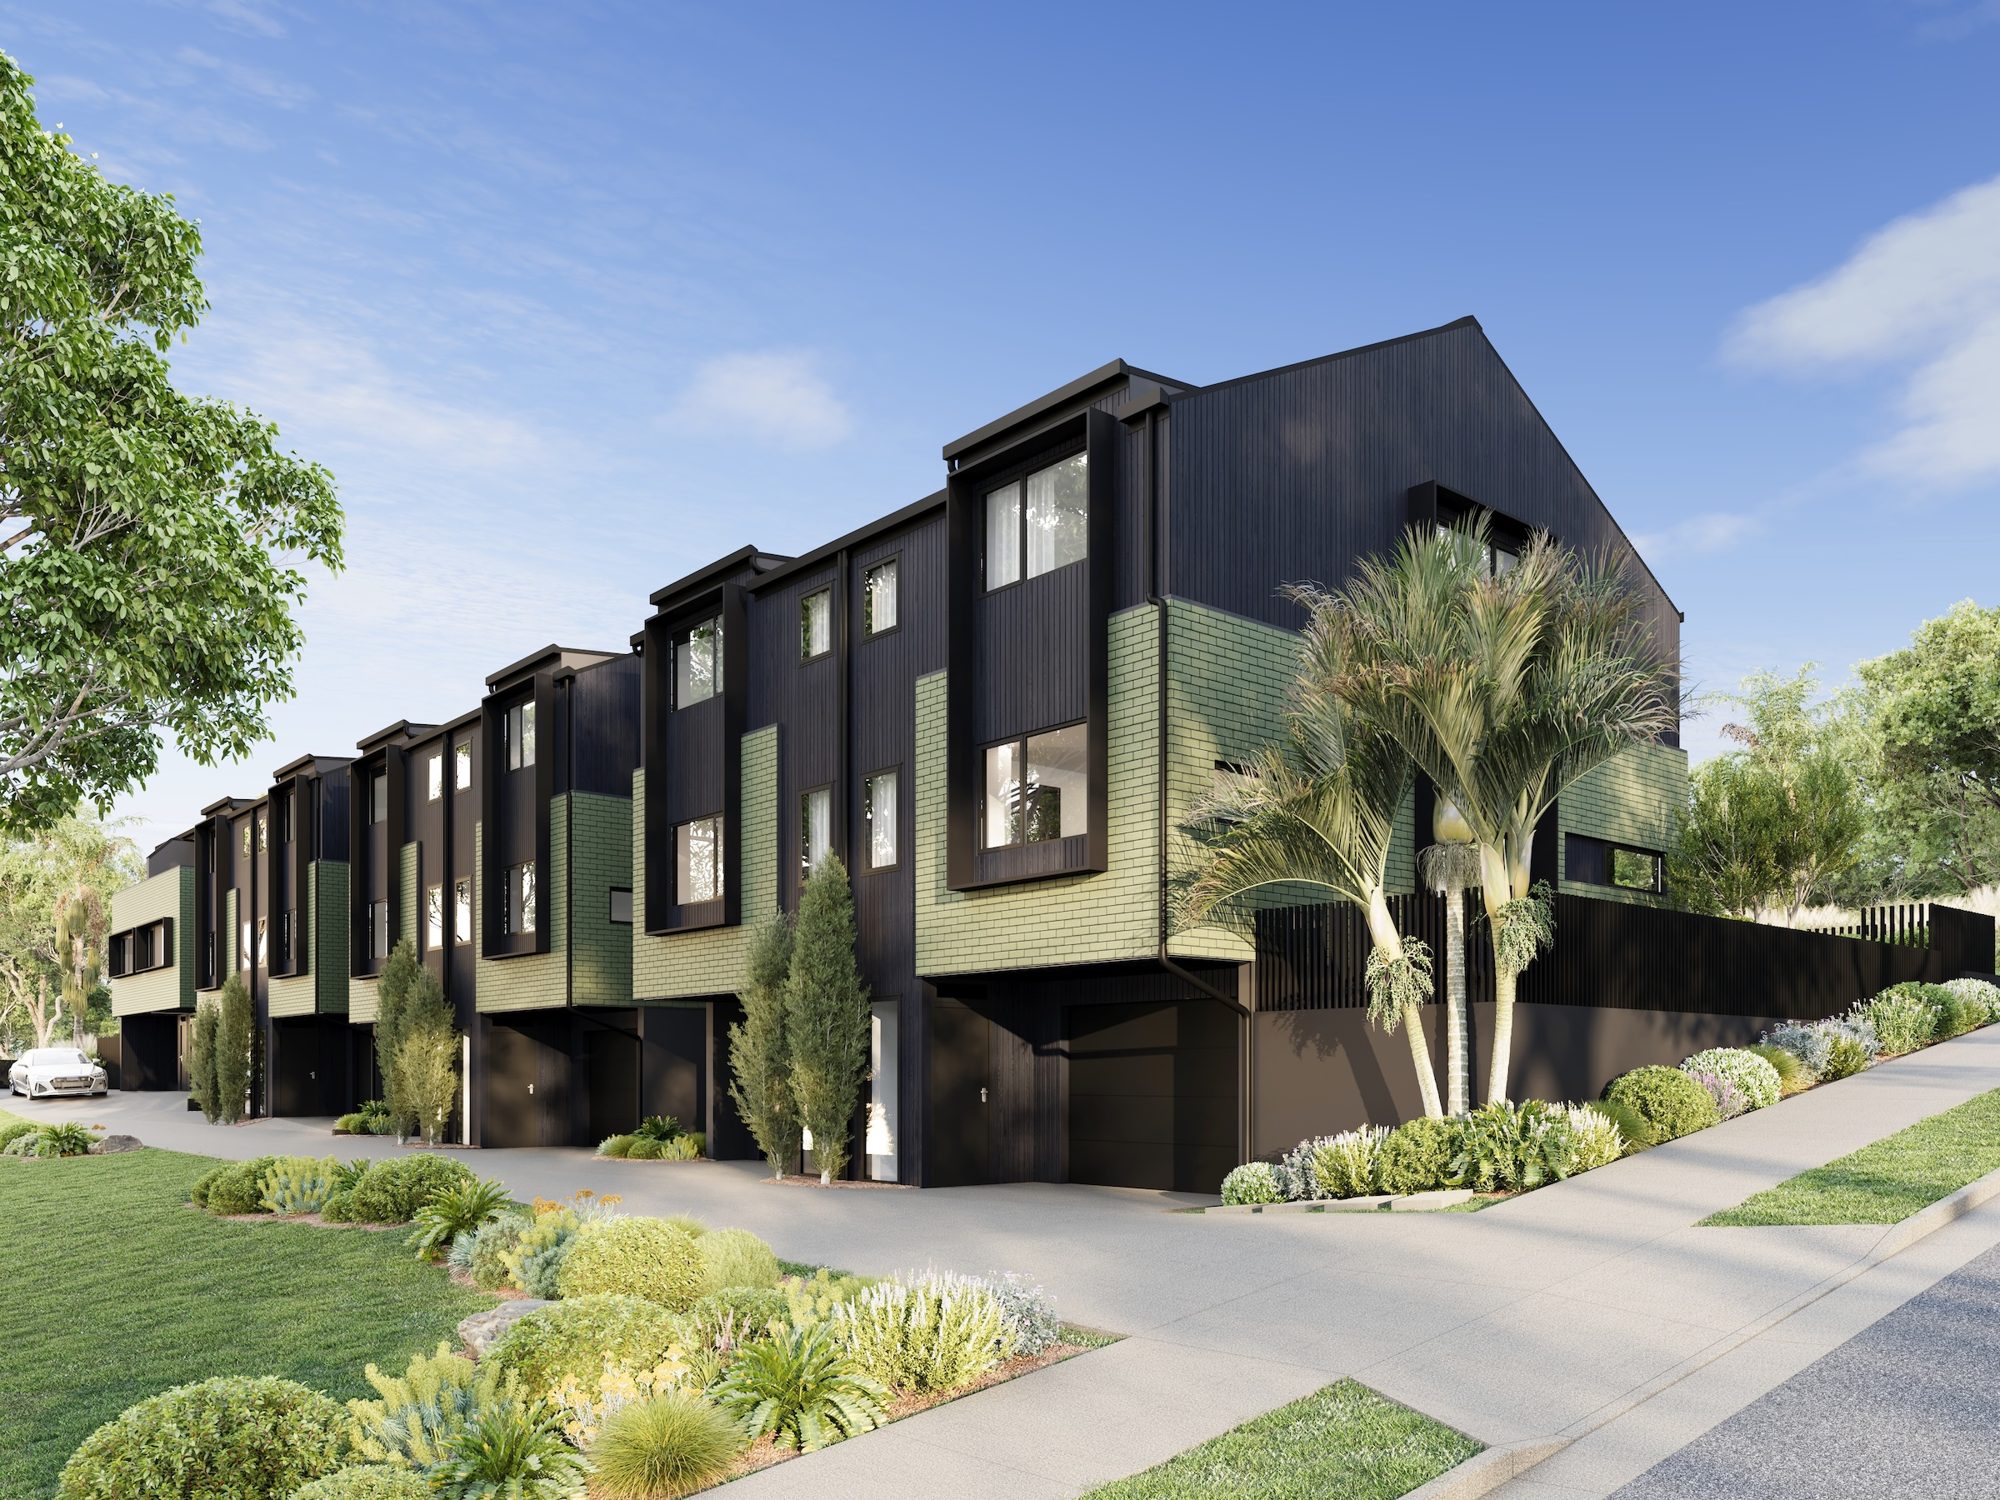
6 Viewland Avenue, 8 townhouses in four duplexes in Onehunga, Auckland (artist's impression) Selling now Artist's impression

6 Viewland Avenue

Onehunga, Auckland

8 townhouses in four duplexes

  • 2 to 3 bed
  • 2.5 bath
  • 1 parking

Price by Negotiation

  • A media flex room in every home
  • Sea views from the top floor of every home
  • Heated LED mirrors, a skylight and a second heat pump upstairs
  • A single internal garage in every home
  • A deck off the living room in every home
  • An ensuite in every home, two in the two-bedroom homes
  • End homes with the most land, up to 164 m²
See the homes

We are a project marketing company. We sell new homes for developers. We do not give financial advice, and nothing on this page is a forecast. For advice on whether a home suits you, talk to your adviser.

06Questions

What investors ask us.

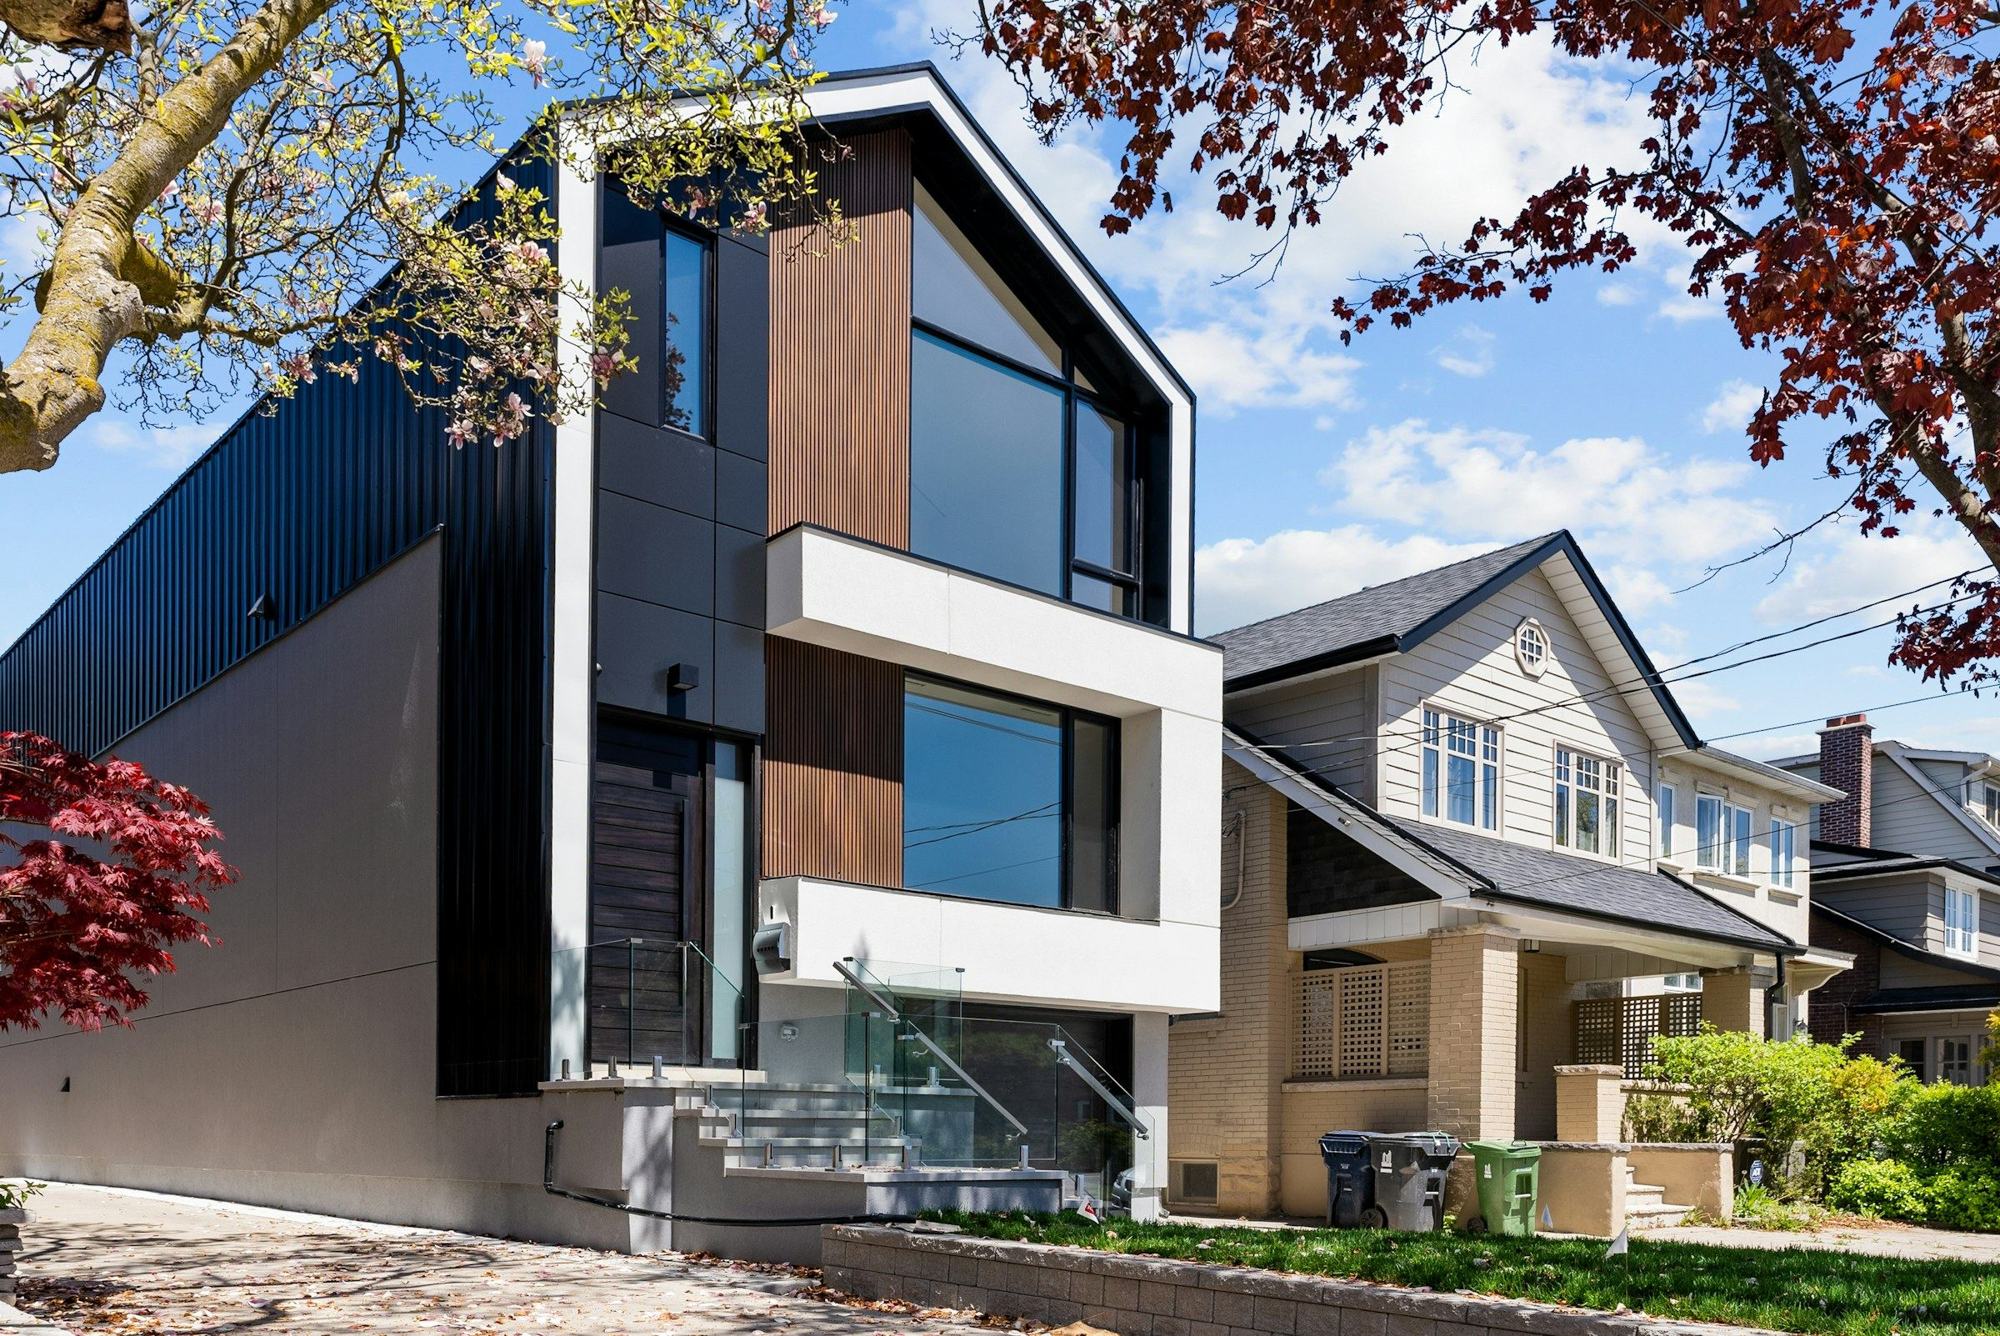
A new townhouse beside an older house on the same street
New, with the cover the law gives it.
Is a new build easier to borrow for?

Often, yes. A loan to buy a home new from the developer is exempt from the Reserve Bank's loan to value limits, so a bank may accept a smaller deposit than on an existing home. Each bank sets its own rules, so ask your lender.

Read the full answer 

What are the tax rules on a new build rental?

As at 2026, interest on a rental loan is fully deductible again, and the bright-line test is two years for any home, new or existing. For an off the plans purchase the two years run from the date you sign. This is general information only; take your own position from an accountant.

Read the full answer 

Can I sell before the home is finished?

Only if the agreement allows it, and that usually needs the developer's consent. A sale within two years of signing is normally taxable under the bright-line test. Ask your lawyer and accountant before you sign if this matters to you.

Read the full answer 

Which home in the development should I pick?

Most buyers weigh aspect, position in the row and the floor plan. In a terrace, an end home shares one wall rather than two. We'll show you the differences; the choice is yours.

Read the full answer 

Can the developer change the finishes?

The agreement says what can change and what cannot. Read it with your solicitor.

Read the full answer 

What happens if completion is late?

The agreement sets out the dates, any sunset date that lets either side cancel, and what happens if dates move. We tell you as soon as we know.

Read the full answer 

Who do you work for?

The developer who is selling the homes. We'll always say so plainly, and we'll recommend you get your own lawyer before you sign.

Read the full answer 

Kingdom Realty

From the first plans to the last key.

Talk to us

Ready to talk?

Tell us whether you're buying or selling a development, and we'll call you within one working day.

The form takes two minutes. A real person calls within one working day, and nothing is signed until you choose to.

Prefer to talk? +64 9 802 7695 or hello@kingdomrealty.co.nz.

Add a note

We use your details to answer this and follow it up, and keep them in our client records. We never sell them. Privacy policy.

Prefer to talk? Call +64 9 802 7695 or email hello@kingdomrealty.co.nz.

The New Build Report

Thanks, you're on the list.

You'll receive the next issue as soon as it's out. Here's the current one to read now.